How much does a manufactured home cost?
Contributed by Karen Idelson
Updated Oct 22, 2026
•11-minute read

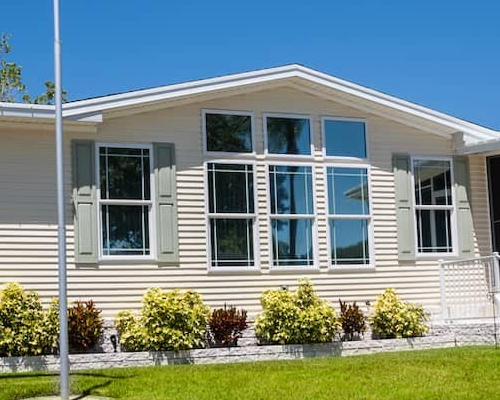
When shopping for a place to call home, finding an option that suits your budget is essential. For many home buyers, the relatively affordable cost of a manufactured home compared to a traditionally built home makes it a worthwhile possibility.
As of 2025, the most recent for which data is available, the average cost of a new manufactured home was $127,200, according to the U.S. Census Bureau. That’s considerably more affordable than the national median home sale price of $393,895 for September 2026, according to Redfin.
But the cost of a manufactured home can vary based on many factors, including base prices, hidden costs, financing, and location. We cover what to know about mobile home prices in this guide.
Key takeaways:
- Manufactured homes are factory–built houses that are built to standards set by HUD and transported to a homesite, then installed.
- Manufactured homes typically cost far less than more traditional single–family homes.
- The cost of a manufactured home is just one piece of the picture. You also need to consider things like renting a site, delivery, and other costs.
What is a manufactured home?
Manufactured homes are factory–built homes that meet the manufacturing standards laid out by the Department of Housing and Urban Development (HUD).
If the structure was built prior to June 15, 1976, it’s considered a mobile home. That’s because there were no standardized safety or construction standards in place at that time. After that date, HUD established a code of minimum standards that all manufacturers must live up to.
Therefore, homes built after that date are considered manufactured homes. It’s very hard to find traditional mortgage financing for a mobile home that existed before June 1976.
See what you qualify for
Manufactured homes vs. mobile homes vs. modular homes
You may hear the words manufactured home and mobile home used interchangeably, but they are two different things and are treated differently by mortgage lenders and insurers.
According to the Department of Housing and Urban Development, a mobile home is a factory–built home that was constructed prior to June 15, 1976. Manufactured homes are those built on or after that date. While the date is the key difference, that date indicates very different standards for safety and construction.
Manufactured homes, unlike mobile homes, must meet HUD’s Manufactured Home Construction and Safety Standards, which means lenders are typically more willing to offer loans for manufactured homes than mobile homes.
A modular home is much like a manufactured home. The main difference is that they typically are delivered in two or more pieces rather than a single piece. They’re also typically built on top of crawlspaces or basements and look more like a traditional home.
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
How much does a manufactured home cost?
According to the Census Bureau, the average manufactured home costs $127,200. However, keep in mind that prices can vary based on size and construction and that figure does not include key costs, such as transportation and installation.
Average manufactured home cost by type
The type of home that you purchase can play a big role in how much you pay for a manufactured home. In general, larger homes will cost more than smaller ones.
|
Average cost of a Manufachured Home |
|
|
Type of home |
Average cost |
|
Single–Wide |
$85,600 |
|
Double–Wide |
$157,100 |
|
Triple–Wide |
$200,000+ |
Manufactured home cost by square footage
The typical new manufactured home costs between $55 and $85 per square foot for base factory–built structures. The precise cost per square foot depends heavily on the layout, builder tier, regional transportation distances, and interior finishes of the home.
For example, a typical single–wide home can range from 600 to 1,300 square feet, while a double–wide usually varies from 1,000 to 2,400 square feet.
Taking the national averages for these home types, the baseline factory cost comes out to roughly $70 to $80 per square foot for a single–wide home (averaging about $85,200 to $88,200 total) and $65 to $75 per square foot for a double–wide home (averaging about $152,000 to $161,200 total). Double–wides often feature a slightly lower per–square–foot base price because expensive, fixed–cost areas like kitchens and bathrooms are spread across a much larger total living footprint.
Base price vs. total manufactured home cost
Keep in mind that the base price of a manufactured home, meaning the amount you pay to the manufacturer to get the home out of a factory, is just one piece of the puzzle. You also must pay for costs related to transporting and installing the home.
A common rule of thumb is the 60/40 rule. This rule states that you should expect 60% of your budget to go toward buying the home and 40% toward site work and placing the home. Put another way, budget two–thirds of the home’s cost for site work and placement.
What the base price may include
The first cost to look at when buying a manufactured home is the base price. This includes the home itself and is typically dependent on the size of the home, its layout, the model, and any selected finishes.
Check the fine print and details of the home carefully, as what’s included in the base price and what is not can vary from one manufacturer to another.
How to estimate site work and placement costs
Once you buy a manufactured home, you have to transport it to a homesite and get it installed. However, before that you also have to make sure the homesite is prepared for the installation, which can involve preparing utility hookups, making sure the ground is level, and pouring the foundation, and so on.
Plus, you’ll have to pay for permitting, tax, and insurance, which can vary from town to town, so even your ZIP code can play a role in how much you pay.
Another consideration is whether you’re renting the land for your manufactured home, which involves ongoing rental fees but may mean the land is more prepared for installation, or buying land, which means a higher upfront purchase price and potentially more costs for site work, but the potential to pay off the mortgage and own the plot outright.
Use this worksheet when coming up with an estimate of the cost to place a home.
- Cost of land lease or mortgage _______
- Site preparation _______
- Pouring foundation _______
- Transportation and delivery fees _______
- Installation fees _______
- Utility hookups _______
- Permitting _______
- Inspections _______
- Taxes _______
- Insurance _______
As with any project involving contractors, it’s worth checking with multiple businesses so you can compare quotes to find the best one for you.
Factors that affect manufactured home prices
The average cost of a manufactured home is determined by many of the same factors that would impact the price of a stick–built or modular home.
We take a closer look at the different factors that impact the cost of manufactured homes below.
Size, type, manufacturer, and finishes
In general, you can expect to pay more for a larger manufactured home, so size and the difference between single– or double–wide plays a big role in the cost. Finishes, meaning the type of flooring, siding, roof material, and so on, can also contribute to cost. High quality or more luxurious finishes will cost more.
As with all products, the manufactured home market is full of many different companies. Some boast a better reputation than others. And you’ll find various price points across the industry.
Generally, it’s a good idea to shop around to find the most affordable options that suit your needs and quality preferences while also considering the manufacturer’s reputation for quality and service.
Delivery, setup, and site preparation
Getting your mobile home to the site is a project unto itself. Typical delivery charges range from $10 to $15 per mile the home needs to travel, so get ready to pay a few thousand dollars to get the home to the site.
The costs can add up quickly. For starters, there’s the size and weight of the home. Depending on how that breaks down, you could need multiple semitrucks. Escorts may also be needed because it’s an oversized load, and you’ll also need permits to be pulled. Finally, if sections need to be transported separately, they’ll need to be reassembled on–site.
Land purchase or lot rent
After buying a manufactured home, you need somewhere to put it. You have the option of buying land on which to place your home or leasing from a mobile home park. If you choose to purchase a parcel of land, you’ll need to know that there is a higher upfront cost. Many may need to consider a land loan, which can significantly escalate their costs.
Expect to pay between $5,000 and $100,000 to buy a plot of land depending on where you’re located or pay rent between $600 and $900 or more each month.
Foundation and utility hookups
When manufactured homes are delivered to the site, they’re transported on a permanent chassis and wheels. To get a traditional mortgage and take advantage of lower rates, lenders will likely require the home to be attached to a permanent foundation instead.
A basic foundation will run you between $7,000 and $15,000, while a more involved permanent slab or basement foundation can be $20,000 or more. As a plus, a permanent foundation may improve your mortgage eligibility, which can make it easier to finance the home.
Once the home is at the site, you’ll have to install utility services like electricity, water, and sewer. If you’re buying land where a home hasn’t been before, that can mean paying to extend service lines too. You may also want to check for any utility easements on the property.
Depending on whether and how far you need to extend service, or if you’re adding a septic system or well, you could be paying between $10,000 and $30,000 for utility hookups.
Taxes, insurance, permits, and ongoing costs
Manufactured homes are subject to property tax and you’ll also need to pay for permits to transport and install the home. You should also make sure to find insurance for your manufactured home.
All of these costs, plus the ongoing costs of renting or paying the mortgage on a homesite and home maintenance, can add hundreds of dollars per month to your housing budget.
Financing a manufactured home
It’s generally more difficult to find a lender willing to finance a manufactured home. But if the home is attached to a permanent foundation, making it real property instead of personal property, your home loan options open up.
Mortgage options for manufactured homes
Here’s a look at some of the common manufactured home loan options for homes permanently affixed to a foundation:
- Federal Housing Administration (FHA). These loans are insured by the Federal Housing Administration and have benefits such as low down payment requirements and easier underwriting.
- Department of Veterans Affairs (VA). VA loans1 are available to veterans and eligible servicemembers and come with benefits such as no down payment requirement and competitive rates.
- U.S. Department of Agriculture (USDA). USDA loans are available to low–income borrowers for properties in designated rural areas and offer benefits such as low down payment requirements and no minimum credit score.
- Conventional. Conventional mortgages are widely available to borrowers with good credit and the ability to make a sufficient down payment. With a large enough down payment, borrowers can avoid paying for private mortgage insurance.
If the mobile home isn’t attached to the foundation, chattel loans or personal loans might provide the appropriate funding. Typically, personal loans come with higher mortgage rates than home loan options.
Financing requirements for manufactured homes
Financing requirements for mobile homes vary based on the lender. But some common requirements include:
- Titling: Typically, the home must be classified as real property instead of personal property.
- Permanent foundation: Most home lenders require that the mobile home be permanently affixed to a foundation.
- Age and model details: To qualify for financing, the home must have been built after June 15, 1976.
Beyond details of the home itself, you’ll need a strong financial application. Most lenders prefer to work with borrowers who have a good credit score, reliable income, and a manageable debt–to–income (DTI) ratio.
Chattel loans and personal loans
If your manufactured home isn’t permanently attached to a foundation or is otherwise classified as personal property rather than real estate, you may not be able to get a mortgage for it. Instead, you may have to rely on chattel loans or personal loans.
A chattel loan is a specialized loan for moveable personal property such as manufactured homes. It is secured by the property purchased with the loan, meaning the lender can repossess the property if you fail to make payments.
A personal loan is a type of flexible loan that can be used for many purposes. It is usually unsecured, so rates can be higher and underwriting requirements are tighter. It also usually has shorter repayment terms than mortgages, which can make monthly payments harder to handle.
Do manufactured homes depreciate?
Every manufactured home is different, so there’s no single answer as to whether a manufactured home will depreciate. Factors such as the condition of the home, how well it’s maintained, the location of the land where it’s located, whether you own the land or the details of the lease, the existence and condition of a permanent foundation, and myriad other factors all impact the home’s long–term value and whether it depreciates. If you own the land, your home value may follow the overall housing market and could appreciate over time. If you lease the land, the home is more likely to lose value.
How to save on manufactured home costs
As you prepare to purchase a manufactured home, a little bit of strategy can help you tap into significant savings.
Compare models, manufacturers, and locations
As with any major purchase, it’s important to shop around to find the best deal. Look at multiple different models of manufactured homes and check with different manufacturers. You might find multiple options that appeal and choose the one that best fits your budget.
Similarly, look at multiple locations for placing your home to find the best deal. You might find a better deal by looking in more rural locations.
Reduce delivery, setup, and upgrade costs
You should also consider ways to reduce the cost of transporting and setting up your home and configuring it to your liking. For example, if you buy during off–peak season you may be able to land a discount on delivery.
It’s also worth negotiating with manufacturers to try to get discounts on upgrades or extras. Negotiating can be easier if you have offers from other sellers to show that they have to compete for your business. Energy–efficient features can also lower your long–term utility costs, so weigh those upgrades against their upfront price.
FAQ
Find answers to your manufactured home questions below.
What is the cheapest price for a mobile home?
On the lower end, mobile homes can cost as little as $85,000 or less, but keep in mind that this is the cost of the home itself. You can expect to pay as much as $57,000 more or so for transportation and installation.
How much does a double–wide manufactured home cost?
The cost to buy a double–wide manufactured home is about $157,000 before accounting for costs such as transportation and installation.
Can I finance a manufactured home?
Yes, you can finance a manufactured home, but financing options can vary. For example, a manufactured home placed on a permanent foundation may be eligible for a more traditional mortgage, while those without a foundation may require a chattel loan or personal loan.
Is it cheaper to live in a manufactured home than in a house?
Manufactured homes may be cheaper to live in than other types of houses, but it depends on many factors. For example, the cost to buy a manufactured home is much lower than the cost of a single–family home, but you also have to account for installation and buying or renting land.
What is the typical lifespan of a mobile home?
Manufactured homes built since 1976 must meet HUD standards for construction, safety, and other factors. This has helped contribute to them having longer lifespans than mobile homes constructed prior to that date. According to a 1990 study by the Manufactured Housing Institute, you can expect a manufactured home to last as long as 50 years or more.
The bottom line
Manufactured homes are generally more affordable than comparable stick–built homes, mainly because the price of the home itself is lower. But the home’s price is only part of the picture. Delivery, a permanent foundation, utility hookups, permits, and either a land purchase or monthly lot rent can add thousands of dollars to your budget. Before you commit, add up the full cost of buying and placing the home, compare quotes from several manufacturers and contractors, and make sure the total fits your budget.
If a manufactured home is the right fit for you, speak to a Home Loan Expert to explore your loan options.
1 Rocket Mortgage is a VA approved lender, not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency.
TJ Porter
TJ Porter has ten years of experience as a personal finance writer covering investing, banking, credit, and more.
TJ's interest in personal finance began as he looked for ways to stretch his own dollars through deals or reward points. In all of his writing, TJ aims to provide easy to understand and actionable content that can help readers make financial choices that work for them.
When he's not writing about finance, TJ enjoys games (of the video and board variety), cooking and reading.
Related resources
10-minute read
Manufactured homes: Defined and explained
Manufactured housing refers to a specific type of prefabricated home and can offer an affordable path to homeownership. Learn the pros and cons and more.
Read more
7-minute read
Is the cost of a mobile home worth it? Pros and cons
Wondering about the pros and cons of a mobile home? Our guide explores whether the low cost is worth its disadvantages in comparison to traditional homes.
Read more
11-minute read
How to buy a manufactured home and land
Learn how to buy a manufactured home and land together, compare loan options, estimate key costs, and prepare your site before closing.
Read more