What is a chattel mortgage and how does it work?
Contributed by Karen Idelson
Updated Oct 25, 2026
•6-minute read

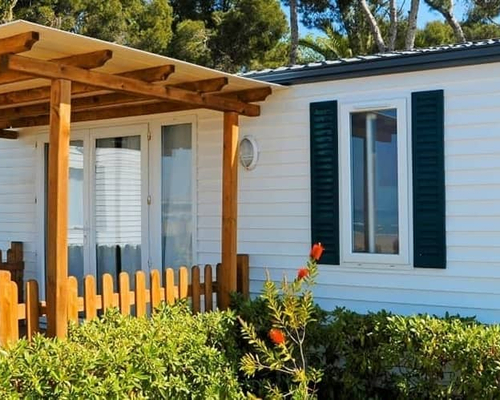
A chattel mortgage is a loan for financing movable personal property, such as a manufactured home, vehicle, or equipment. The financed property secures the loan, giving the lender the right to seize it if the borrower fails to honor the loan agreement.
Rocket Mortgage does not currently offer chattel mortgage loans. However, we can educate you on this and other types of loans to help you decide which is best for your situation.
Key takeaways:
- A chattel mortgage finances movable personal property, such as manufactured homes, business vehicles, or commercial equipment, using the financed item as collateral.
- Compared with traditional mortgages, chattel loans often have shorter terms and lower processing fees, but they tend to carry higher interest rates and fewer lender options.
- Rocket Mortgage doesn’t currently offer chattel mortgage loans, but we can help you understand your financing options.
What is a chattel mortgage?
A chattel mortgage finances movable personal property as opposed to land or other real estate. Let’s dive deeper into the meaning of chattel and related terms.
What chattel means
Chattel is a legal term for movable personal property. Think manufactured homes that aren’t attached to the land, vehicles, and farm equipment. By contrast, real property refers to land and anything permanently attached to it, such as buildings, trees, and mineral deposits.
Key chattel mortgage terms
Some other mortgage terms you should know that are related to chattel mortgages include:
- Debtor: This is the borrower, the one who owes the chattel mortgage debt to a lender.
- Secured party: This is the lender, the one who holds a secured interest in the chattel property.
- Collateral: This is the property that the borrower pledges to guarantee the chattel mortgage (in most cases, the property being financed). If the borrower defaults, the lender can seize the collateral and sell it to help recoup their losses.
- Lien: This is the secured interest that the lender holds in the chattel property. If the borrower defaults, the lender may exercise this interest by seizing the property.
- Security agreement: This is the contractual agreement between borrower and lender that creates the lender’s secured interest in the chattel property.
See what you qualify for
How does a chattel mortgage work?
Here’s how a chattel mortgage works:
Application and approval
First, you must apply for a chattel mortgage from a lender. This involves sharing details about your finances and the property to be financed. The lender will then approve or reject your application based on this information.
Collateral, liens, ownership, and title
If approved, the chattel loan turns the financed property into collateral for the lender. This means that they retain a secured interest in the property until it’s paid off. Meanwhile, you generally receive use or legal ownership of the property.
Payoff, default, and repossession
Once you pay off the chattel loan, the lender’s claim on the property expires. However, missing payments or defaulting on the loan may lead to the lender seizing or repossessing the property.
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
What are chattel loans used for?
Chattel loans can be used for all of the following:
Manufactured, mobile, and modular homes
Chattel loans can be used to finance manufactured or mobile homes on leased lots, in rented parks, or in land-lease communities.
The difference between a manufactured and a mobile home is largely when the home was built. A mobile home is a structure built prior to June 15, 1976, while a manufactured home is one built after that date when new U.S. Department of Housing and Urban Development (HUD) guidelines were put into place.
Relatedly, a modular home is any building, other than a manufactured or mobile home, that is of closed construction and is either entirely or substantially prefabricated or assembled at a place other than the building site. Often, you can get conventional financing for a modular home since they typically are fixed to the land as real property. Learn how modular and manufactured homes differ.
Vehicles and boats
Chattel mortgages can also finance vehicles and boats. What makes these loans different from conventional car loans and boat loans is that a chattel loan is used for business vehicles. In other words, the car or boat must be used for commercial purposes.
Business equipment and farm machinery
A chattel mortgage can also finance construction tools, tractors, forklifts, farm machinery, and other commercial equipment to be used as collateral on the loan.
Find out if a 30-year fixed loan is right for you
See rates, requirements and benefits
Chattel mortgage vs. traditional mortgage and personal loan
It’s important to distinguish chattel loans from traditional mortgages and personal loans:
Chattel mortgage vs. traditional mortgage
A chattel mortgage can finance and collateralize only movable assets. It cannot do the same for land or structures attached to land (aka real estate), which require a traditional mortgage, such as a Federal Housing Administration (FHA) loan. A manufactured home that sits on a permanent foundation and is titled together with the land may qualify as real property, which can open the door to a traditional mortgage.
Chattel mortgage vs. personal loan
A chattel mortgage is always secured by collateral. However, a personal loan can be secured or unsecured. Furthermore, personal loans tend to have fewer restrictions on how the funds can be used, while chattel mortgages are meant to finance movable personal property only.
When each option may make sense
Chattel financing may be best for financing a movable home on leased land or commercial equipment. Meanwhile, traditional financing is better for homes attached to land. Personal loans may be a good option for debt consolidation, emergency expenses, or home repairs.
Chattel mortgage requirements, rates, terms, and fees
Let’s go over what it takes to get a chattel mortgage.
Is it difficult to get a chattel loan?
Not necessarily. Chattel loan approval varies by lender and their risk appetite. It also depends on your creditworthiness, income stability, debt-to-income ratio (DTI), and the value and condition of the collateral.
Chattel mortgage rates and repayment terms
Chattel loans generally have higher rates and shorter repayment periods than traditional mortgages. However, rates and terms vary by lender and loan program. You can compare current mortgage rates for traditional loans.
Processing fees and down payments
Chattel mortgages often have lower processing fees than traditional mortgages. However, fees and down payment requirements vary. Ask your lender for more details. Keep in mind that the cost of a manufactured home can include delivery, installation, and site preparation.
Chattel mortgage pros and cons
Before getting a chattel mortgage, consider the pros and cons:
Potential benefits
On the one hand, chattel mortgages often offer shorter loan terms, lower processing fees, and less stringent credit requirements.
Potential downsides
On the other hand, chattel mortgages tend to have higher interest rates, and there are fewer lenders to choose from.
How to get a chattel mortgage
To get a chattel mortgage, follow these steps:
Find and compare chattel mortgage lenders
First, seek out lenders that offer chattel loans. While Rocket Mortgage doesn’t currently offer chattel mortgage loans, we can help educate you on your options.
Prepare for the application
Once you’ve chosen a lender, verify their application requirements and submit the necessary financial and property documents.
Review the terms before signing
Before signing any loan documents, review the loan terms, including the interest rate, fees, down payment requirements, and collateral provisions. Also, carefully weigh the risk of your property being repossessed to ensure you’re comfortable with it. A mortgage calculator can help you estimate payments on a traditional loan.
Tax implications of a chattel mortgage
You can usually deduct the interest you pay on a chattel mortgage from your annual income for tax purposes. You may also be able to claim depreciation on the asset itself as long as it’s used for business purposes. However, tax benefits depend on the property type and use. If you own the land and the home is fixed to it as real property, you may also be able to take advantage of property tax deductions. Consult a tax professional to learn more.
FAQ
Here are answers to some frequently asked questions regarding chattel mortgages:
What is an example of a chattel mortgage?
Imagine you want to buy a manufactured home to put on a rented piece of land. A chattel mortgage can finance the home, which serves as collateral. You own the home, but the lender can seize it if you stop making payments before the loan is fully repaid.
How many years is a chattel mortgage?
Chattel mortgage loan terms vary by lender and loan program but tend to be shorter than conventional mortgage repayment periods.
What credit score do you need for a chattel mortgage?
Credit requirements for a chattel mortgage are lender-specific and vary as a result. Furthermore, creditworthiness is only one of many factors that lenders may evaluate.
The bottom line
A chattel mortgage is a loan that finances movable personal property, such as manufactured homes, business vehicles, or commercial equipment, with the financed property serving as collateral. These loans often come with shorter terms and lower processing fees, but they also tend to carry higher interest rates and give you fewer lenders to choose from.
Rocket Mortgage doesn’t currently offer chattel mortgage loans. However, if you’re buying or refinancing a home that’s permanently attached to land, a traditional mortgage may be worth exploring. You can reach out to Rocket Mortgage and apply for a loan today.
Christian Allred
Christian Allred is a freelance writer whose work focuses on homeownership and real estate investing. Besides Rocket Mortgage, he’s written for brands like PropStream, CRE Daily, Propmodo, PropertyOnion, AIM Group, Vista Point Advisors, and more.
Related resources
9-minute read
Manufactured home loans: What buyers should know
Learn how manufactured home loans work, including FHA, VA, conventional, and chattel options, key requirements, and costs. Compare paths and apply today.
Read more
11-minute read
How to buy a manufactured home and land
Learn how to buy a manufactured home and land together, compare loan options, estimate key costs, and prepare your site before closing.
Read more
13-minute read
How to finance manufactured and mobile home loans
Mobile home loans can work differently than traditional mortgages. Read on to see your financing options, requirements, and how to qualify.
Read more