Energy-efficient mortgage: A guide for borrowers
Contributed by Karen Idelson
Updated Sep 6, 2025
•9-minute read

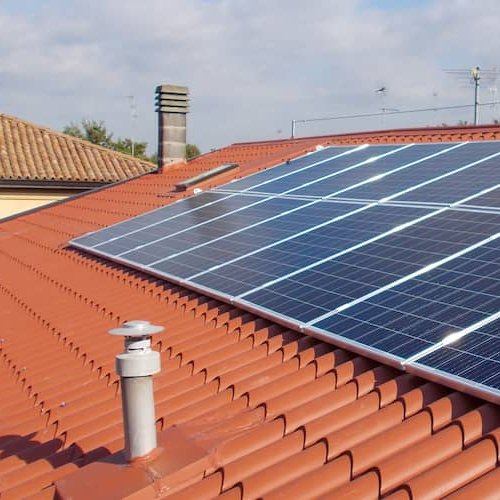
If you’ve felt a bit of sticker shock when opening recent utility bills, you’re certainly not alone. Across the country, energy bills have increased significantly in recent years, with electric bills skyrocketing by close to 30% for many households since 2021. As a result, building an energy-efficient house has become a rising trend. If you already own an existing home, one way to lower your utility bills is by making energy-efficient renovations to your home.
Making eco-friendly upgrades will not only help keep your energy costs down, but they can also add substantial resale value to your property. You don’t need a complete overhaul to see results. Simpler energy-efficient methods like utilizing smart appliances and installing double-pane windows can make a meaningful difference. Let’s take a look at some ways you can make your home more energy-efficient to help save money on energy costs.
What is an energy-efficient home?
An energy-efficient home is one that uses less energy to run by reducing waste. Many homes, particularly older ones, use more energy than they actually need. Energy-efficient homes eliminate waste using modern technology and updated systems, which lowers utility bills and reduces air pollution. While your home might've come with appliances, they might be outdated or using more energy than necessary. There are a variety of minor updates and larger renovations that can make a big difference when it comes to your energy costs.
Here are some common systems and devices that tend to contribute the most to energy usage:
- HVAC systems: Your heating, ventilation, and air-conditioning systems tend to consume the most energy of all your home’s systems.
- Hot water heaters: A hot water heater can use electricity, gas, or solar thermal energy to heat water for the home and consume energy even when they’re not being used.
- Kitchen appliances, washers, and dryers: The appliances that cook and store food and wash your clothes consume a significant amount of energy – especially refrigerators and freezers.
- Lighting systems: Your home's lighting systems can also contribute a sizable amount to your electricity bill.
- Overall electrical systems: These are all the components that receive and transmit electrical power and typically include the breaker box, wiring, and outlets.
See what you qualify for
How to make your house more energy-efficient
While it might seem like an expensive or overwhelming endeavor, taking steps to make your home more eco-friendly can save you a significant sum over time. Here are some ways to make yours an energy savings home.
1. Do a home energy audit
Consider a DIY or professional home energy audit to assess how much energy each system of your home is using. That way, you can pinpoint what parts of your home are the best candidates for energy-efficient improvements. An energy audit can involve reviewing past utility bills, checking the exterior for cracks and gaps, and inspecting appliances, insulation, and other aspects of the interior.
Keep in mind that some electric companies offer this service entirely for free. Depending on the company and the specifics of the program, a free energy audit also can mean income-qualified efficiency programs and rebates.
2. Install solar panels
Solar panels convert sunlight into electrical energy in one of two ways: through photovoltaic (PV) panels or mirrors that essentially concentrate solar radiation.
In 2026, the average cost of solar panels was roughly $30,000, but this depends on factors like the type of solar panel and size. While this is a hefty price tag, federal and local incentives can help bring down the cost, allowing you to maximize your solar panel savings. According to EnergySage, solar panels can recoup their cost over 25 - 30 years of electricity savings.
A solar loan can also help fund this upgrade. While they’re similar to home improvement loans, solar loans are designed for just the purchase and installation of solar panels.
3. Unplug vampire electronics
You might be surprised to know how many appliances and devices are sucking energy just by being plugged in – even when turned off. They’re called vampire electronics, and they may be adding to your electric bill needlessly. Examples include any device that has an indicator light, clock, or remote control that can contribute anywhere from 5% - 20% to the average home electric bill. According to The Office of the Ohio Consumers’ Counsel, the average home has anywhere from 20 – 40 vampire electronics.
For instance, you may leave a toaster plugged in all the time, even though you only use it twice a week. Meanwhile, the appliance is using a small amount of energy just by being plugged into an outlet. To stop this invisible drain on your utility bill, we recommend unplugging power strips and appliances when not in use whenever possible.
| Pros | Cons |
|---|---|
| Potential utility bill savings | More challenging underwriting process |
| Potential increase in home equity | Possible longer approval time |
| Improved home comfort and style | Not all improvements are eligible |
| Smaller environmental footprint | Fewer loan options |
| Enhanced climate resilience |
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
Types of energy-efficient mortgage programs
Home buyers can pick from several EEM loan programs. Each type offers unique features and benefits and has different eligibility requirements.
FHA loan energy-efficient mortgage program
The FHA’s EEM program is available to borrowers with a 15-year or 30-year FHA loan with at least 3.5% home equity or a 3.5% down payment. The loans are offered for detached homes, townhouses, and eligible condominiums.
The improvement must be deemed “cost-effective,” demonstrating that the home improvement will pay for itself over time, and cannot exceed 5% of the property’s value, up to an $8,000 limit.
Credit scores and other requirements apply to FHA loans, but they may allow you to get an EEM with more flexible terms. Learn more about FHA loans to better understand if the program could make sense for your homeownership goals.
What do FHA EEMs finance?
The list of potential projects you could use funds from an FHA EEM for is extensive. While you must stay within FHA EEM guidelines, potential projects could include:
- ENERGY STAR appliances
- Renewable energy sources
- Sealing and weatherization
- Insulation enhancements
- Smart energy systems
- LED lighting
- Tankless or solar water heaters
- High-performance windows
- HVAC systems
Remember, the program’s focus is on lowering energy use and maximizing savings. Improvements for new homes must exceed the International Energy Conservation Code requirement, and existing home improvements must pay for themselves over time.
VA loan energy-efficient mortgage program
The VA’s loan program also allows for energy-efficient mortgages. This add-on program is for eligible military households, veterans, and surviving spouses looking to make money-saving efficiency improvements as part of a mortgage loan for a new purchase or an Interest Rate Reduction Refinancing Loan (IRRRL).
The VA loan program limits borrowers to $6,000 for EEM-related borrowing. Improvements must be completed within six months of closing the loan to be eligible for EEM funds.
What do VA EEMs finance?
You should always seek approval at the start of the EEM process to ensure your upgrade is covered. For the VA, you can contact your regional VA loan center with specific questions.
Examples of covered projects could include:
- Sealing and weatherization
- Clock thermostats
- Insulation
- Solar heating and cooling
- Gas and electric furnace upgrades
- Thermal doors and windows
USDA Single Family Housing Guaranteed Loan Program
While the USDA Single Family Housing Guaranteed Loan Program isn’t specifically an energy-efficient mortgage, it can help low-income to moderate-income home buyers fund eligible rural home purchases and upgrades, and those can include efficiency. Even outside of EEMs, many efficiency upgrades are a good investment regardless.
Down payment, income, and property requirements vary by location. If you’re looking at a home in a suburban or rural area, you may want to learn more about USDA loans.
Conventional energy-efficient mortgage programs
Conventional mortgages are loans conforming to standards set by Fannie Mae and Freddie Mac, large government-sponsored enterprises (GSEs) that play an important role in the mortgage industry.
With a conventional mortgage, you can borrow up to 15% of the property’s appraised value for green improvements. That’s a generous limit compared to other EEM programs.
What do Fannie Mae EEMs finance?
You can use a Fannie Mae HomeStyle Energy Mortgage for more than just energy efficiency projects. You can also use this energy-efficient mortgage for projects that make your home more resilient against climate change, buy ENERGY-STAR® certified products, and more. Allowed uses include:
- Upgrades to energy and water systems, including solar panels, wind power devices, and geothermal systems
- Basic weatherization (e.g., insulation, sealing, etc.) and water-efficient items (up to $3,500)
- ENERGY STAR®-certified products
- New windows and doors for improved efficiency
- Resiliency upgrades to protect against natural disasters, including:
- Storm surge barriers
- Foundation retrofitting for earthquakes
- Hazardous brush and tree removal in fire zones
- Retaining walls for mud or water flow prevention
- Radon remediation
- Environmental hazard damage repairs
- Paying off energy-related debt, including:
- Entire PACE lien amounts (for purchase or refinance)
- Prior energy-related improvements (up to 15% of property value with refinance)
The Fannie Mae HomeStyle website is the best place to find the latest details. You may find that even some past purchases are eligible, even if you paid for them with a HELOC or other loan.
What do Freddie Mac EEMs finance?
Freddie Mac offers the GreenCHOICE mortgage, its version of an EEM. GreenCHOICE is very similar to HomeStyle from Fannie Mae. The project can also be for up to 15% of the home’s appraised value, and other conventional mortgage terms apply.
Examples of projects eligible for a Freddie Mac GreenCHOICE mortgage include:
- Programmable thermostats
- Caulking and weather stripping
- Ceiling, wall, or floor insulation
- Air sealing
- High-efficiency air conditioning and heating system replacements
- Solar water heaters
- Low-flow water fixtures
- High-efficiency refrigerators, freezers, water heaters, and light bulbs
- Replacement of windows and doors
To learn more, visit the official Freddie Mac GreenCHOICE loan website.
EEM eligibility requirements
Homeowners must meet lender requirements to be approved for an energy-efficient mortgage, including minimum credit score requirements, documentation guidelines, and verifying that the energy-efficient improvements are cost-effective.
To be demonstrated as cost-effective, the upfront price of the energy-efficient upgrades must be less than your expected energy savings over time.
For some EEM programs, an energy consultant must conduct an energy audit as part of the application process. The audit uses the Home Energy Rating System (HERS) to measure your current energy efficiency and estimate your potential energy savings after the proposed EEM-funded upgrades. The cost of energy-efficient home improvements can also include generating the energy rating report and conducting related inspections.
A lender will consider your estimated savings on your energy bills as part of your qualification and underwriting process, and applicants must also meet the financial requirements of their mortgage loan type.
Is an EEM right for you?
EEMs are typically best suited for homeowners who want to save on utility bills and want long-term value. They’re also popular with buyers who want to invest in home solar panels and other cost-effective technologies.
Even if you don’t want an EEM, if an efficient upgrade will pay for itself through utility savings or home appreciation, the project could be a worthwhile undertaking.
However, if you don’t plan on staying in the home for at least a few years, there’s a good chance you won’t break even on the EEM. Make sure you plan to stay in the home long enough to earn back your energy-efficient investment before committing to an EEM.
Alternatives to an EEM
If you don’t qualify or an EEM isn’t what you’re looking for, you can use other options to fund your energy-efficient home improvement projects, such as projects backed by your home equity or personal loans.
Cash-out refinance
With a cash-out refinance, you can swap out your existing mortgage for a new, larger mortgage and pocket the difference to fund your eco-friendly upgrades. If you’ve owned your home for several years and have built up equity, a cash-out refinance could be a good solution.
Look at the interest rate and other costs when deciding whether to refinance or keep your existing loan.
Home equity loans and lines of credit
With a home equity loan, you can withdraw a portion of your equity and convert it to cash to finance your energy-efficient improvements. A traditional home equity loan is an installment loan, sometimes called a second mortgage, that’s paid off with fixed payments. A HELOC allows you to borrow up to a credit limit. With both a HELOC and home equity loan, your loan is backed by the value you’ve built up in your home.
Personal loans
Unlike the other options we discussed, a personal loan is typically an unsecured loan. Personal loans commonly offer a fixed monthly payment over a set period, but they’re not attached to your home or any other collateral.
With no collateral, however, you can expect to pay a higher interest rate. Comparing risks and costs is key when deciding on a home equity loan or a personal loan for a home improvement project.
Complementary FHA options
If a personal loan, home equity loan, or cash-out refinance doesn’t work, the Federal Housing Administration offers complementary EEM programs or policies that may fit with your goals.
- Section 203(k) rehabilitation mortgage: You can combine an EEM with a Section 203(k) rehabilitation loan, stacking improvements from the energy package over the improvements you can make with a 203(k) loan.
- Energy Efficient Homes (EEH): If your home meets Energy Efficient Home (EEH) standards, the FHA will stretch borrowing limits by 2%, which may help you qualify for a larger loan. You can use the stretch ratios with any FHA insurance Title II program.
- Solar and wind technologies: The program allows borrowers to increase their mortgage amount to cover the installation of new wind or solar energy systems when purchasing or refinancing a home.
- Weatherization: You can finance up to $3,500 to cover weatherization items, such as thermostats or insulation.
FAQ
When shopping for an energy efficient mortgage, these are among the most common questions:
Do energy-efficient mortgages offer tax advantages?
Paying for eligible green upgrades may qualify you for federal home energy tax credits, which can reduce your overall tax liability. These credits often apply to improvements like solar panels, insulation, and high-efficiency appliances. Learn more about home improvement tax deductions.
How can I find energy-efficient mortgage lenders?
Start by researching lenders that specialize in energy-efficient mortgages, such as those offering FHA Energy-Efficient Mortgages (EEMs) or programs like Fannie Mae’s HomeStyle® Energy and Freddie Mac’s GreenCHOICE®. Compare rates, terms, and experience with green loans. These are similar steps to choosing a mortgage lender, regardless of whether you want an EEM loan.
How much can I borrow with an energy-efficient mortgage?
The amount you can borrow depends on your income, credit profile, property value, and loan program limits. In many cases, the cost of energy upgrades can be financed on top of the home’s appraised value, provided they meet program guidelines.
Can I use an energy-efficient mortgage to upgrade an existing property?
Yes, if you already own a home, you can use a refinance loan to roll the cost of qualifying energy-efficient upgrades into your mortgage. This allows you to make improvements while spreading the costs over the life of the loan.
What does “cost-effective” mean for energy-efficient mortgages?
In this context, cost-effective means that the projected savings from the energy improvements are expected to justify the upfront costs. Lenders often assess whether the upgrades will reduce utility expenses enough to cover the project cost.
The bottom line: An energy-efficient mortgage can be worth it for the potential savings
Energy-efficient mortgages can be a powerful tool for homeowners who want to invest in their homes and their future. By financing upgrades that can lower utility costs, boost comfort, and increase your home’s value, these loans can make sustainable living more accessible. They’re available through popular programs like FHA, VA, USDA, and conventional mortgages, giving many borrowers a chance to align their housing goals with their values.
Even though Rocket Mortgage® doesn’t currently offer energy-efficient mortgages, Rocket Mortgage offers other loan options.
Rocket Mortgage is a VA-approved lender, not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency.
Eric Rosenberg
Eric Rosenberg, is a financial writer, speaker, and consultant based in Ventura, California. He holds an undergraduate finance degree, an MBA in finance, and is a Certified Financial Education Instructor (CFEI®). He is an expert in banking, credit cards, investing, cryptocurrency, insurance, real estate, business finance, and financial fraud and security.
He has professional experience as a bank manager and nearly a decade in corporate finance and accounting. His work has appeared in many online publications, including USA Today, Forbes, Time, Business Insider, Nerdwallet, Investopedia, and U.S. News & World Report.
Related resources
12-minute read
What is a 30-year fixed-rate mortgage?
A 30-year fixed mortgage is common among homeowners who prefer stable payments. Learn more about this mortgage so you can decide if it's your best option.
Read more
8-minute read
15-year vs. 30-year mortgage comparison
Which loan term fits your budget? Comparing 15-year vs. 30-year mortgage options shows significant differences in rates, payments, and total interest paid.
Read more
5-minute read
When should I refinance my mortgage?
Refinancing a mortgage can let you borrow equity or reduce your interest rate, but it also costs money. Learn more about when it makes sense to refinance.
Read more