Loans for flipping houses: A complete guide
Contributed by Tom McLean
Updated Sep 4, 2026
•10-minute read

Loans for flipping houses are typically short-term and asset-based, sized to a property’s after-repair value (ARV) and structured to fund both purchase and renovations on a tight timeline. This guide breaks down your best loan options, what they cost, and how to choose the right fit based on your equity, credit, reserves, experience, and project schedule.
Key takeaways:
- Most fix-and-flip financing is short-term and asset-based, so lenders weigh the property’s after-repair value more heavily than your paycheck.
- Your budget must cover four things: purchase price, renovation costs, carrying costs, and selling costs.
- The right loan depends on your equity, credit, cash reserves, project experience, and how fast you plan to sell.
What is a loan for flipping houses?
A loan for buying a flipped house is short-term financing. Most of these loans run 6 to 18 months instead of 15 or 30 years for a mortgage, and are used to buy a property, pay for renovations, and carry it until it’s sold.
These loans are asset-based, which means the value of the property itself carries more weight in the approval decision than your income does.
How fix-and-flip loans work
Fix-and-flip lenders typically fund the purchase at closing and hold the renovation money in a separate account you can draw from in stages as work is completed and inspected.
Payments on the loan are often interest-only during the term, with the principal due when you sell or refinance. That keeps your monthly cost low but sets a hard deadline for completing the flip.
How lenders determine your loan amount
Two numbers drive most fix-and-flip loan offers:
- The loan-to-cost ratio compares your loan amount to the combined purchase and renovation budget.
- The loan-to-ARV ratio compares your loan amount to the after-repair value.
What that means for your cash:
- Because the lender is underwriting what you expect the house to be worth instead of what it’s worth now, it builds in a cushion.
- Plan on a down payment of roughly 20% to 25% of the purchase price. For example, on a $250,000 property, a 25% down payment comes to $62,500.
What after-repair value means
The after-repair value, or ARV, is the estimated worth of the home once renovations are finished.
Lenders set ARV using comparable sales of completed homes nearby, not the current condition of your fixer-upper.
It is the most important number in a flip, because it caps your loan and defines your profit. If your renovation scope does not increase the property’s value into the same range as the comps, the home may not be worth flipping.
See what you qualify for
Costs and requirements before financing a flip
The financing will cover part but not all the cost of a flip. Aspiring flippers should consider these four categories when putting together a budget and before talking to a lender.
Purchase price
This is your acquisition cost. It includes your down payment, plus lender fees, title costs, and any inspections you order.
Most flip profit is determined when you buy, not when you sell. That means the greater the discount you get when you buy a home, the greater the profit you can expect to earn when you sell.
Knowing how to find houses to flip matters as much as the renovation. Distressed listings, auctions, and off-market deals are where the margin usually lives.
Renovation costs
Renovation is the largest line item on most flip projects and the most difficult to pin down.
For example, the average cost of renovating a 1,250- to 1,600-square-foot home is roughly $52,000, but the full range of costs can run from $3,000 for light cosmetic work to $190,000 for a full overhaul.
Get contractor bids in writing before you close, and hold back a contingency amount to pay for any surprises that come up.
Carrying costs
Carrying costs are what you pay to own the property while you fix it. Every extra month you own a property eats into your profit margin, which is why timeline discipline matters as much as the renovation budget.
Here are the typical carrying costs to account for:
- Interest. Fix-and-flip loans usually have interest rates well above conventional mortgage interest rates. Many require interest-only payments until you sell, so this cost runs every month the project is open.
- Utilities. Water, electric, gas, and trash keep running while the house sits empty. Call the local providers for an estimate rather than guessing, since rates vary by market.
- Taxes. Property taxes accrue the whole time you hold the title, and they vary widely by state and county. You also may have to pay tax on your profit when you sell. Any profit on a property you own for 1 year or less is considered a short-term capital gain and taxed as ordinary income. A profit on a property owned longer than a year qualifies as a long-term capital gain and is taxed at a lower rate.
- Insurance. A vacant home under renovation usually needs a builder's risk policy rather than standard homeowners insurance. Most lenders require proof of insurance before funding.
- HOA fees. If the property belongs to a homeowners association, you’ll have to pay HOA fees regardless of whether anyone lives there.
Selling costs
When it is time to sell, plan for agent compensation, closing costs, title and escrow fees, and staging or photography if you list it yourself. Real estate agent commissions are negotiable, so treat any percentage you hear quoted as a starting point.
Common loan requirements
Requirements vary by lender and loan type, but most fix-and-flip lenders want solid credit, a down payment in the 20% to 25% range, liquid reserves to cover overruns, and a defined renovation scope backed by contractor bids. Investors with completed projects on record generally get better pricing and higher leverage than first-timers.
Personal loans
Personal loans can be used for just about anything, including a down payment and renovation costs for house flipping. They can come from banks, credit unions, and other institutions and have a lot of flexibility with requirements, interest rates, and loan terms. They’re also pretty easy to apply for. However, personal loans are generally for lower amounts compared to mortgages, and often have higher interest rates.
Consider a personal loan if:
- You don’t need too much money and can probably keep it in five figures
- You don’t want to put your house or anything up as collateral
Hard money loans
Hard money loans are short-term loans that require collateral, often a house, and have a short application process. You can usually get your money quickly, within a week, and you’ll have a shorter time to pay it back. These loans come from private lenders and have more flexibility when it comes to requirements, though they can have high interest rates.
A hard money loan might be ideal for you if:
- You’re having trouble applying for traditional mortgages
- You don’t want a long repayment term
- You’re an experienced house flipper who knows you can renovate and sell quickly
Rehab loans
Rehab loans are also known as fix-and-flip, or renovation, loans. They require appraisals and have a similar application process to mortgages, though they are short-term. How much money you can get will depend on the after-repair value (ARV) of a home. Because this is estimated before the house is actually fixed, you can usually only borrow 75% of the estimate in case things don’t go as planned.
Keep in mind that some government-backed rehab loans, like the 203(k) Rehabilitation Mortgage, require residency and are not suitable for investment properties.
These loans can be a good option if:
- You’re looking for a short-term loan
- You’re an experienced house flipper and are confident your home can meet or exceed the estimated ARV
- You don’t want to put your primary residence up as collateral
Bridge loans
A bridge loan is a short-term loan often used to cover expenses between when someone purchases a home and when a larger loan or mortgage is approved. These can be risky if there’s a chance proper funding doesn’t work out. Interest rates are also usually high.
You might want to go for a bridge loan if:
- You’re fairly certain you’ll get long-term funding
- You found a property you simply can’t wait on
- You have a back-up plan if long-term funding fails
- You have a credit score of at least 740 and a DTI of less than 50%
Loans from personal connections
If you want to try an alternative route, or you have the right connections, you can always go the personal route. Maybe you have friends or family members who will go in on the project with you. You could also look for a real estate investment partner or even consider crowdfunding.
These might be good options for you if:
- You already have connections in the world of real estate investing
- You have experience in crowdfunding
- You want to avoid high interest rates
- You’re willing to try a less conventional approach
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
Types of loans for flipping houses
There is no single best loan for flipping houses. Each option below trades speed for cost, or cost for risk.
Cash-out refinance loans
If you own a primary residence or other property with enough equity, a cash-out refinance will allow you to borrow that equity to finance renovations for your flip. Fannie Mae requires that at least one borrower has been on title for 6 months and that the first mortgage being paid off is at least 12 months old, so this is not a quick-turn play.
Home equity loans and lines of credit
You also can borrow equity on a property you already own with either a home equity loan or a home equity line of credit (HELOC). A home equity loan pays out as a lump sum at a fixed rate. A HELOC works like a revolving line of credit you draw from as renovation bills arrive. The tradeoff with taking out a second mortgage on a property you own is that the home itself serves as collateral, and a lender can foreclose if you default.
Rocket Mortgage currently doesn’t offer HELOCs, but it does offer Home Equity Loans.
Personal loans
A personal loan is unsecured debt, so no collateral is required, and approval is fast. Borrowers with good credit and a low debt-to-income ratio (DTI) may qualify for up to $100,000. Interest rates on personal loans are higher than they are on mortgages secured with collateral. For most flips, personal loans work better as gap funding than as the primary loan.
Hard money loans
Hard money loans come from private lenders and are secured by the property. Approval leans on the deal rather than your income, which makes them the default choice for investors who cannot qualify for conventional financing.
Rehab loans
Rehab or renovation loans let you borrow the purchase amount and the renovation budget for a primary residence with a single loan based on the property’s ARV. Government-backed FHA 203(k) loans are available to home buyers and homeowners, HUD-approved nonprofit organizations, and government agencies, which leaves out private investors.
Bridge loans
A bridge loan is short-term financing to cover the gap between buying one property and securing longer-term financing or selling another. Terms are short, and rates run high, so this works only when you are confident the exit is coming. If you own a home with equity, compare a bridge loan vs. HELOC before you commit.
Loans from personal connections
Friends, family, or an investment partner can fund a flip faster and cheaper than any lender. Make sure to put the terms of any loan in writing. The IRS applies below-market loan rules to gift loans between individuals, and the usual $10,000 exception does not apply when the money is directly used to buy or carry income-producing assets like a flip.
Business lines of credit
If you run several projects at once, a revolving business line of credit gives you capital you can draw, repay, and draw again without reapplying. Lenders generally want an established business entity, a track record, and a personal guarantee. This is a tool for repeat flippers.
Peer-to-peer lending
Peer-to-peer lending, sometimes called crowdfunding, pools money from individual investors through an online platform. You pitch the project, and funders decide whether to back it. Rates vary widely depending on your credit profile, the loan amount, and the platform.
401(k) loans
Some employer plans let you borrow from your 401(k) retirement savings to make a down payment on a home. The IRS caps plan loans at 50% of your vested account balance or $50,000, whichever is less, and repayment is generally required within 5 years. That 5-year window extends only when the loan is used to buy a principal residence. If you leave your job, the outstanding balance can come due right away.
Seller financing
With seller financing, the seller acts as the lender, and you pay them directly on terms you negotiate together. It can work when a seller owns the property free and clear and wants a steady income more than a lump sum. Have an attorney document the agreement. It is also a common route for anyone learning how to invest in real estate with limited cash on hand.
Who offers loans to flip houses?
Your funding sources fall into four groups. Banks and credit unions offer the cheapest money, but rarely finance short-term flips. Hard money and private lenders move fastest and cost the most. Fintech lenders sit between the two. Crowdfunding platforms suit investors who are comfortable pitching a deal to strangers.
How to compare lenders
The rate alone will not tell you which offer is better. Compare the elements of your Loan Estimates from lenders directly.
- Total cost. Interest rate plus origination points, underwriting fees, and draw inspection fees.
- Coverage. What share of the purchase price and renovation budget each lender funds.
- Draw process. How renovation money is released and how many days each inspection takes.
- Speed to close. How fast the lender can fund once you are under contract.
- Exit terms. Prepayment penalties, extension fees, and what happens if you run past the term.
Questions to ask before applying
Here are some questions to consider asking a lender before submitting your application:
- What is your maximum loan-to-cost and maximum loan-to-ARV?
- How are renovation draws released, and how long does each one take?
- Do you require prior flip experience, and does it change my pricing?
- What does an extension cost if I need more time?
- What fees apply beyond the interest rate?
How to get a loan to flip a house
Here are three steps to getting a loan for a home you plan to flip.
1. Understand your financing needs
Start with the deal, not the loan. Add up purchase price, renovation budget, carrying costs, and selling costs, then subtract that total from a realistic ARV. If the spread is thin, no financing structure will save the project. This is also where you decide whether to flip at all, since flipping versus renting leads to completely different loan products.
2. Evaluate your qualifications
Pull your credit reports, calculate your DTI, count your liquid reserves, and document any projects you have completed. Lenders financing an investment property purchase underwrite reserves closely, because they need to know you can absorb a delay without missing payments.
3. Compare lenders
Get written terms from at least three lenders and compare the full cost, not just the headline rate. Ask each to walk you through a sample draw schedule on a project like yours. The fastest lender is rarely the cheapest, and on a short timeline, speed sometimes wins.
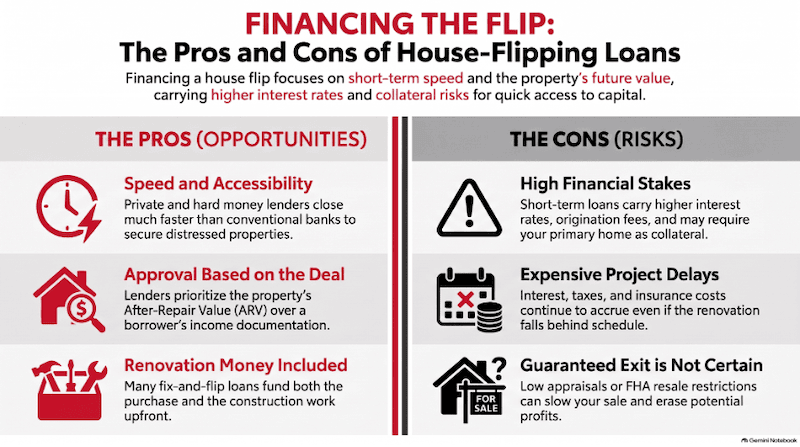
Pros and cons of house-flipping loans
FAQ
Here are answers to common questions about loans for flipping houses.
What kind of loan is best for flipping houses?
Hard money and fix-and-flip loans suit investors who need speed and renovation funding in one package. Home equity products cost less if you already have equity and can accept the collateral risk. Match the loan to your timeline, reserves, and experience.
What is the 70% rule in flipping?
The 70% rule is an industry guideline suggesting you pay no more than 70% of a property’s ARV minus estimated repair costs. It is a screening shortcut, not a regulation, and it does not account for carrying costs or financing charges. Read more on the 70% rule in house flipping.
What is the $100,000 loophole for family loans?
It refers to a limit in the IRS below-market loan rules. On gift loans between individuals of $100,000 or less, the imputed interest the borrower is treated as paying is capped at their net investment income for the year, and if that income is $1,000 or less, it is treated as zero. The cap disappears once loans between the two people exceed $100,000, and it does not apply if avoiding federal tax is a main purpose of the arrangement. Talk to a tax professional first.
What are fix-and-flip loan requirements?
Expect a lender to look at your credit, your down payment, your liquid reserves, your renovation scope and contractor bids, and your history with prior projects. The property itself gets underwritten separately through an ARV appraisal.
How fast can hard money lenders close?
Hard money lenders are built for speed and typically close faster than conventional mortgage lenders, since they underwrite the property more than the borrower. Actual timelines vary by lender, so ask for a specific commitment in writing before you rely on it in an offer.
Can I use an FHA 203(k) rehabilitation mortgage to flip a house?
No. HUD lists the FHA 203(k) program as available to home buyers and homeowners, HUD-approved nonprofit organizations, and government agencies, so it is not built for investors buying to resell. If you are on the other side of the transaction and buying a flipped house, it is worth understanding the FHA flipping rules that apply to your loan.
The bottom line on loans for flipping houses
Financing a flip means choosing among short-term, asset-based loans like hard money and rehab loans, equity-based options like a cash-out refinance or home equity loan, and alternative sources like partners, seller financing, or a business line of credit. Each price speeds, costs, and risks differently. The right choice comes down to your equity, credit, reserves, project experience, and timeline. Run the numbers on the deal before you shop the loan, compare full costs rather than headline rates, and know the risk on every dollar you borrow.
If you are still deciding what kind of investor to be, micro flipping and construction loans are worth a look, along with whether you need a real estate license to flip houses.

Jasica Usman
Jasica is a Licensed Real Estate Agent (Texas #795679), a writer, and marketing professional with hands-on experience guiding buyers and sellers through contracts, negotiations, and new-construction transactions. She brings a practical, market-informed perspective to real estate and mortgage topics, with a focus on clear, consumer-first education.
Related resources
6-minute read
How to find houses to flip
Learn how to find houses to flip online, off-market, and through distressed sales, plus what to evaluate before buying. Start your search smarter.
Read more
16-minute read
Investment property loans: Options and requirements
Explore investment property loans, requirements, down payments, and financing options so you can compare paths and start your mortgage application.
Read more
13-minute read
How to finance an Airbnb rental: A guide for investors
You can get an Airbnb loan to buy houses to use as short-term rentals. Learn how you can use income from Airbnb rentals to get a mortgage.
Read more