How to buy land and build a house
Contributed by Maggie McCombs
Updated Oct 15, 2026
•9-minute read

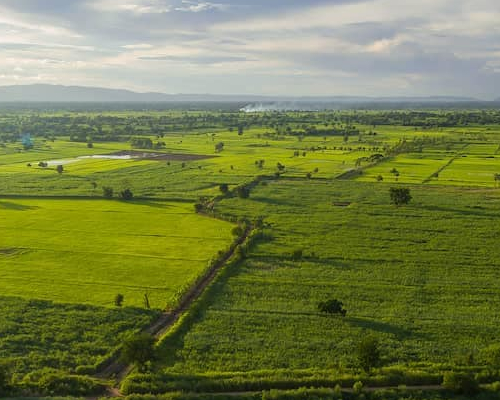
Buying land and building lets you choose the location, layout, and features, but it requires more steps than a typical purchase. You need to vet the land, line up financing, hire a builder, get permits, and manage construction.
Rocket Mortgage doesn’t offer construction loans or land loans, but we can help you when it comes time to convert to permanent financing. Learn more about how the process works, what it costs, and how to decide if it’s right for you.
Key takeaways:
- Check zoning, utilities, road access, soil, and title before you close on land, ideally during a feasibility contingency period written into your offer.
- Land and construction financing works differently from a standard mortgage, with larger down payments on land loans and construction funds paid out in stages.
- Custom homes often take close to a year or longer from permit to completion, so build extra time and money into your plan.
Why build a home?
Most people build because they want something they can’t find on the market, especially in markets with low housing inventory. You can design the floor plan around how you live, choose your finishes, and settle anywhere the land is buildable instead of wherever homes happen to be for sale. And because everything is new, you won’t inherit a previous owner’s aging systems or hidden repairs.
See what you qualify for
How much does it cost to buy land and build a house?
Your cost to build a house depends on location, land prices, site preparation, labor, materials, permits, utility hookups, and the home’s size and features. Undeveloped land also may need clearing, grading, a driveway, and utility connections before construction begins.
For scale, a 2026 National Association of Home Builders (NAHB) study found that permit, hookup, inspection, and other government fees paid by builders during construction averaged $20,154 per new home, or 6.4% of construction costs. Material costs are climbing, too. In July 2026, residential building material prices were up 5% from a year earlier, and softwood lumber prices were up 17.3%, so keep an eye on lumber prices as you budget.
How much does it cost to buy land?
Land prices vary widely depending on location, size, and how ready the property is for building. Lots for newly built homes had a national median value of $59,000 for single-family homes started in 2025, according to the NAHB analysis of Census Bureau data.
Regional medians ranged from $50,000 in the South Atlantic and East South Central Census divisions to $170,000 in the Pacific division.
Rural land can cost far less per acre. U.S. pastureland averaged $2,000 per acre in 2026, and cropland averaged $6,020 per acre, according to the U.S. Department of Agriculture (USDA).
Keep in mind that raw land may need clearing, grading, utilities, and road access before you can build, so a lower price upfront doesn't always mean a lower total cost.
Is it cheaper to buy land and build a house?
Often, no. Once you add land, site work, construction, and financing, building usually costs more than buying, though your market matters. The median contract price for a contractor-built home started in 2025 was $404,000, and that doesn’t include the land. The median price of a new builder-sold home in 2025, lot included, was $417,400. Compare building a house vs. buying where you want to live before you commit.
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
How to finance buying land and building a house
Financing land and construction works differently from financing an existing home because there’s no finished house to secure the loan at the start. Talk with lenders that finance local construction before you make an offer.
Land loans
A land loan pays for the lot. Lenders see land as riskier than a home, so these loans typically have larger down payments, higher interest rates, and shorter terms than a standard mortgage. Many include a balloon payment, meaning the remaining balance comes due in one lump sum at the end of the term.
Construction loans
A construction loan can finance both the land and the building process. Unlike a standard mortgage, which pays out the full loan amount at closing, a construction loan releases money as construction progresses.
Construction-to-permanent loans
A construction-to-permanent loan combines construction financing and your long-term mortgage. With a single-closing version, you close once, and the loan automatically converts to a permanent mortgage when construction is finished. If you buy the lot in the same transaction, the purchase price used to size the loan includes the lot price and the cost of construction.
Construction draws
Construction money is paid out in stages, called draws, as the build moves forward. With a single-closing construction-to-permanent loan, the lender manages payments to the builder, contractors, or suppliers. On FHA construction-to-permanent loans, funds left after the land purchase are held in escrow, and your lender needs your written authorization before each draw.1
Land contracts and personal loans
- Land contracts: With a land contract, also called a contract for deed, the seller finances the purchase and keeps the deed until you’ve paid in full. Have a real estate attorney review the terms.
- Personal loans: Banks, credit unions, and online lenders offer personal loans you can use for almost any purpose, including a small land purchase.
Down payments and preapproval
Land loans usually require more cash up front, while construction-to-permanent loans follow their program’s rules. A VA-backed purchase loan, for example, can be used to build a new home and requires no down payment as long as the price isn’t higher than the appraised value.2 Get preapproved before you make an offer so you know what lenders will need for the lot, builder, and plans.
How to buy land and build a house in 7 steps
Here are the steps to take to buy land a build a home.
1. Choose a location and establish your budget
Start by deciding where you want to live, weighing your commute, schools, amenities, and whether you want urban, suburban, or rural living. Then set a budget for land, site work, construction, permits, and surprises. If cost comes first, research the cheapest places to build a house.
2. Find suitable land
Browse land listings on Redfin and other sites, or work with a real estate agent who specializes in vacant land and can surface listings you might miss.3 Know what you’re shopping for in your next home. A lot in a developed neighborhood is often prepped for construction with utilities in place, while raw rural land may need significant work and may be more difficult to finance.
3. Make an offer with a feasibility contingency
Your agent can help you write an offer with the right contingencies. For land, a feasibility contingency is key. It gives you a due diligence window to investigate the property and walk away if it can’t support your home. Ask for enough time to schedule a survey, soil testing, and utility checks.
4. Complete land due diligence
- Survey and title: Get a land survey to confirm boundaries and easements. You’ll also want to order a title search. Claims against a property can come from a previous owner’s unpaid taxes or unpaid contractors.
- Soil and septic: Septic systems are common where there’s no public sewer, and they rely on the soil to absorb and treat wastewater. Ask whether your area requires a percolation test and note the slope and drainage.
- Utilities: Confirm electricity, gas, water, and sewer availability, and get quotes to connect or drill a well.
- Legal road access: Make sure the parcel has recorded legal access to a public road.
- Zoning and restrictions: Review zoning laws, setback rules, minimum square footage requirements, HOA guidelines, and deed restrictions.
5. Hire your build team and plan the home
Your team typically includes your agent, an architect or designer, and a licensed builder. Interview several builders, check references, and review each contract’s price, timeline, payment schedule, and warranty.
Then plan your home design, lot layout, budget, and schedule. Your lender likely will need the signed builder contract. For FHA construction-to-permanent loans, it must include the builder’s price to build.
6. Secure permits, approvals, and ownership
Your builder should pull the building permit and any plumbing, electrical, or environmental permits your area requires before work starts. You’ll also close on the land.
If you’re financing, your lender must give you a Closing Disclosure at least 3 business days before closing. Resolve any title issues, and once conditions are met, you’ll be clear to close. An owner’s title insurance policy can protect you if someone later claims an interest from before your purchase.
7. Build the home and manage construction draws
If this is your first site-built home, expect some phases to move fast and others to stall. Stay in close contact with your builder, review each draw request before approving it, and consider new construction phase inspections. Plan for a long timeline. Single-family homes completed in 2025 by a hired contractor on the owner’s land took about 11.7 months from permit to completion, and owner-built homes took about 14.3 months.
What to avoid when buying land to build a house
- Skipping a zoning check: Confirm the parcel allows the home you want.
- Assuming utilities are available: Get quotes before you commit.
- Overlooking legal access: Land without recorded road access is hard to build on, finance, or sell.
- Ignoring the soil: Poor drainage can add costs or rule out septic.
- Missing title problems: Clear liens before closing.
- Underfunding the project: Line up land and construction financing, and plan for any balloon payment.
- Starting without permits: Wait until every required permit is issued.
Is buying land to build a house right for you?
Pros
- A home built around you: You control the layout, finishes, and features.
- More location choices: You can build anywhere the land is suitable.
- New everything: Modern systems and materials mean fewer immediate repairs.
Cons
- Higher costs: Land, site work, and construction often add up to more than buying.
- Longer timelines: A custom build can take a year or more; compare that with how long it takes to buy a house.
- More complexity: You’ll manage due diligence, multiple professionals, permits, draws, and possible delays.
FAQ
Here are answers to common questions about how to buy land and build a home.
Can I just buy land and build a house?
Yes, but not right away. First, you’ll need financing, zoning that allows a home, utilities or alternatives like a well and septic, legal road access, and approved permits. Confirm what you need before you buy so you don’t end up with land you can’t build on.
Can I combine loans for my land and home?
Yes. A construction-to-permanent loan can finance the land and construction, then become your long-term mortgage. Options include conventional loans, FHA construction-to-permanent loans, a VA construction loan, and USDA construction loans for eligible rural areas. Rocket Mortgage doesn't currently offer construction loans or land loans, but once your home is complete, we may be able to refinance your construction loan into a permanent mortgage.
Is $200,000 enough to build a house?
It can be in some places, but it’s well below typical costs. A budget of $200,000 is less than half the 2025 median contract price for a contractor-built home, before land. At NAHB’s average of about $162 per square foot, it would cover roughly 1,235 square feet of construction, with nothing left for the lot, site prep, or utilities. If your budget is tight, explore the cheapest ways to build a house, like kit homes or prefab homes.
Is it smart to buy land and build later?
It can be if you’ve found the right location or price but aren’t ready to build. Many lenders don’t require immediate construction, though some set a deadline. Loan payments, property taxes, and any balloon payment still come due while the land sits.
What is the typical down payment to buy land?
Land usually requires a bigger down payment than a house. Lenders might require up to 50% down on a lot loan, and undeveloped land typically requires more than a developed lot because it’s riskier.
Do I have to work with a real estate agent to buy land?
No, but it can help. If you find a real estate agent who knows vacant land, they can help you find and evaluate parcels, negotiate, and keep due diligence on track.
Does buying land and building a home come with tax benefits?
Some, mostly once construction begins. The IRS doesn’t let you deduct mortgage interest on land you plan to build on. After construction starts, you can treat the home as a qualified home for up to 24 months if it becomes your qualified home when it’s ready for occupancy. Review tax deductions for homeowners and talk with a tax professional.
The bottom line: Buying land and building a house offers flexibility
Buying land and building gives you control over where you live and what your home looks like. It also takes careful budgeting, the right financing, thorough due diligence, permits, and hands-on construction management. If you’d rather move sooner, buying a new construction home or an existing home may be a better fit. When you’re ready, start a mortgage application with Rocket Mortgage.
1 Rocket Mortgage is not acting on behalf of FHA or HUD.
2 Rocket Mortgage is a VA-approved lender, not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency.
3 Rocket Mortgage is an affiliate of Redfin. You aren't required to use its lending services. Learn more at redfin.com/afba.
This article is for informational purposes only and is not intended to provide, and should not be relied on for, medical, legal, financial, investment, or tax advice. You should consult with a qualified professional for advice specific to your situation. Consumers should independently verify that any services, products, or programs referenced meet their needs and comply with applicable requirements.
Rocket Mortgage and Redfin are trademarks or service marks of Rocket Mortgage LLC or its affiliates.

Jasica Usman
Jasica is a Licensed Real Estate Agent (Texas #795679), a writer, and marketing professional with hands-on experience guiding buyers and sellers through contracts, negotiations, and new-construction transactions. She brings a practical, market-informed perspective to real estate and mortgage topics, with a focus on clear, consumer-first education.
Related resources
6-minute read
Low housing inventory: How it affects the real estate market
Low housing inventory results from an increase in demand for houses without the supply to meet it. Understand how this affects the real estate market.
Read more
6-minute read
Highest and best offer: What buyers should know
A highest and best offer might be requested by a seller who has received multiple offers on their home. Learn more about this offer and its potential impact....
Read more
4-minute read
How long do sellers have to accept an offer? What to expect after you submit
Learn how long sellers have to accept an offer to purchase real estate in most circumstances. Learn what affects timing, plus what to do if there’s no res...
Read more