Vacant home insurance: Coverage, cost, and what to know
Contributed by Sarah Henseler
Updated Aug 16, 2026
•9-minute read

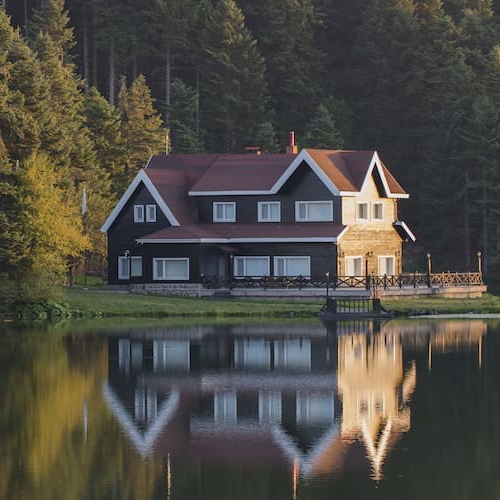
If you own a home that’s going to sit empty for any significant length of time, you might wonder whether your regular homeowners insurance policy will cover it. The answer is probably not. That’s because regular homeowners insurance policies often include a vacancy clause that limits or excludes coverage if your home is left vacant for more than a month or two.
So, for everything from inclement weather, fire, and plumbing leaks to vandalism, theft, and personal liability, you likely need a vacant home insurance policy. It can save stress, time, and a lot of money if anything happens. So let’s explore what this policy covers, what it costs, and how to find the right policy for your situation.
Defining vacant home insurance
Vacant home insurance is designed to protect homes that sit empty for long periods of time, typically more than 30 – 60 days, depending on the policy.
There is also usually a very specific definition when it comes to a “vacant home.” For instance, most insurers distinguish between a vacant home and an unoccupied one, in addition to the time it’s empty.
How vacancy clauses work
If you have a homeowners insurance policy, it probably includes a vacancy clause. This limits or suspends certain types of coverage if you leave your home vacant for a lengthy period, which is specified in the policy. Typically, it’s 30 – 60 consecutive days.
Vacant homes often pose a greater risk than occupied ones because any issues can go unnoticed for weeks. For example, imagine a burst pipe. In an occupied home, it’s likely discovered within hours. In a vacant home, it could cause thousands of dollars of damage before anyone knows about it. The same with break-ins, vandalism, or fire.
If you know your home will be vacant for longer than your standard policy allows, it’s a good idea to call your insurer. They may be able to issue a vacant home insurance policy that keeps coverage in place.
Vacant homes vs. unoccupied homes
In the everyday world, these terms may be used interchangeably. But in the home insurance world, they’re treated very differently.
A vacant home typically lacks furniture and is sitting empty. An unoccupied home, on the other hand, has furniture, utilities, but no occupants – at least for a while. But the idea is that the unoccupied home is in a state in which the owner could return and live at any time. For instance, a home used seasonally would be an example of an unoccupied home. A rental property between renters for months, an empty home for sale, or a home under construction are examples of a vacant home.
This is an important distinction since if you have a vacation home that is furnished, with utilities, but that you leave unoccupied for months out of the year, you might still need a special policy. But that policy will likely be different from a vacant home policy. You’ll need to check with your insurer.
Common reasons a home becomes vacant
There are any number of reasons a home can become vacant. Here are some common ones.
- The owners have relocated and the home is listed for sale.
- A rental property sits empty between tenants.
- The house is undergoing major renovations or repairs.
- An investor purchases a property to renovate and flip.
- Someone inherits a home and is deciding whether to sell, rent or move in.
- The home is foreclosed on and bank-owned.
See what you qualify for
What does vacant home insurance cover?
When you purchase a vacant home insurance policy, it will probably cover a list of named perils. In other words, you’re not necessarily covered for every bad thing that can happen. And while policies vary depending on the insurance company and type of home, here are the common categories of what vacant home insurance covers, and what to know about each.
Fire, smoke, and weather-related damage
Your vacant home insurance will typically cover damage to the structure of your home from accidental fires, electrical fires, and many weather-related events, like lightning, windstorms, or hail. However, exclusions may apply depending on your location and insurer, so you need to read any prospective policy carefully to make sure it fits your needs.
Vandalism, theft, and burglary
As you might imagine, vacant homes are often attractive, low-risk targets for thieves, vandals, and even squatters. These can be insured against, but many insurance companies treat these as add-on endorsements. In other words, they don’t include them automatically; you must purchase them separately and add them on to your policy.
Water intrusion and undetected hazards
Water damage can be a major issue in a vacant home, causing very expensive damage. Even small leaks that go unnoticed for a long time can have big ramifications. So, many vacant home insurance policies cover plumbing failures or burst pipes, but neglected maintenance or flooding are often excluded. Because policies vary widely, it’s important to know exactly what yours includes.
Liability coverage
Liability coverage protects you if someone is injured while on your property. With a vacant home, this can still happen, either from a visitor, maintenance worker, or trespasser. Some vacant home insurance policies include liability protection, while others treat it as an add-on or endorsement. So here again, check any policy you are considering carefully.
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
What vacant home insurance doesn't cover
While having vacant home insurance is important, it doesn’t protect you against every costly incident. It’s important to understand its limitations.
Coverage that may require an endorsement
There are certain protections that may be important for you to have, but are not covered in a standard vacant home insurance policy. This coverage may be available through optional endorsements, however. Depending on the insurer, coverage for vandalism, theft, liability, sewer backups, or valuable personal property may need additional coverage.
Why you should read the policy carefully
There really is no one standard vacant home insurance policy. Each insurer defines coverage slightly differently, with one company providing coverage for certain things that another doesn’t.
Also, you should pay attention to deductibles, exclusions, maintenance requirements and vacancy time limits. Make sure these meet your needs, and you can meet any requirements the policy demands.
Should I have homeowners insurance for vacant homes?
In short, yes. In fact, if you have a mortgage on the property your lender might well require you to have it. If you own the property outright, it’s still a good idea. If anything happens, you could sustain major repair bills or legal costs.
These are very real dangers since most agree that the risk to vacant homes is often more significant than occupied ones. For instance, vacant homes are more vulnerable to squatters and vandalism. They also can be more likely to have serious fire and other damage since problems are not caught early.
So vacant home insurance can really pay off in the long run. If your home becomes vacant, then your homeowners insurance policy company can help you transition to a vacant home policy, or possibly give you an endorsement, or add-on, to your homeowners insurance policy.
Where can I get insurance for my vacant home?
Vacant home insurance is usually easy to find. Big-name insurers like USAA, Farmers, and Progressive all offer policies. In addition, there are many other companies who do as well. The important thing is to shop around.
Generally, it’s a good idea to:
- Start with your current homeowners insurance provider. They may offer an add-on or endorsement to your current homeowners policy.
- Compare quotes. Different providers offer different rates and coverage.
- Compare policy duration minimums. Some companies write policies in 3- or 6-month increments, some only offer 12-month policies. So, there’s no need to pay for more than you need.
- Check local providers: If you live in an area with unique risks, like hurricanes or wildfires, local insurers might have a policy that fits your needs better.
How much is vacant home insurance?
There’s no getting around it, vacant home insurance will almost certainly cost you more than standard homeowners insurance. How much more depends on the specifics of your location, property, and insurer. Some estimates put it at 25% – 50% higher, while others say it might be double or even triple the cost of your standard homeowners policy. With the national average price of homeowners insurance at $2,863 annually, the cost can be significant.
Why vacant home insurance costs more
Insurance companies generally charge higher premiums because vacant homes are more likely to experience costly claims. This is due to the added risks that come with a vacant property, as mentioned above. Issues that could be minor maintenance issues can become major problems when unnoticed.
Simply put, more risk equals higher premiums. But more risk also equals more reason to have insurance. So take this consideration seriously.
Factors that may influence the cost
If the above figures scare you, remember, there are many factors that can affect how much you’ll pay for vacant home insurance, some of which you can control. Here are some common factors that can influence your policy’s price:
- Location. Higher-risk areas, such as places in wildfire zones or high-crime neighborhoods, will increase premiums.
- Condition. Homes that are well-maintained with plumbing and electrical in good condition will cost less to insure.
- Security measures. Properties with cameras, motion-sensor lights and other security measures could lower premiums.
- Vacancy duration. The less time a property is expected to be vacant, the less the policy should cost.
Policy terms and flexibility
The length of the policy you need can affect the price. Some insurers offer 3- or 6-month policies, while others only offer annual ones. Also, choosing the exact coverage you need for your situation is important.
How do I buy vacant home insurance?
The process of buying vacant home insurance is pretty straightforward, and similar to buying homeowners insurance. Here are the steps you should follow:
- Determine if you need vacant home insurance. If your home has no furnishings and will be empty for more than 30 days, there’s a decent chance you’ll need vacant home insurance.
- Check your current coverage. If you have a homeowners insurance policy for the property, your current insurer might offer an endorsement or add-on that will cover your property once it’s vacant. If not, they might offer a smooth transition to a new policy.
- Research insurers. Make sure you trust the company you insure your home with, especially if they are not one of the major brands in the business. Saving a little money now could cost you a lot of headache or money later.
- Get several quotes. This is a major decision on a major investment, so it pays to get multiple quotes. It also provides peace of mind when you do make a final decision.
- Make sure the policy fits your needs. It’s pointless saving money on a policy that doesn’t cover something essential, and it’s just as wasteful to spend more for coverage you don’t need.
When you’ve found the perfect policy, sign on the dotted line and enjoy the comfort of knowing your property is protected.
How to protect a vacant home
Insurance is only one part of protecting a vacant home – a part you’d rather never need. Another vital aspect is prevention. Here are three key ways to protect your vacant home. Many insurers will also require some form of maintenance schedule.
Security
Install quality deadbolts, exterior lighting, motion sensors, and security cameras if possible. Today’s smart home monitoring systems can also be truly beneficial. They can alert you if someone trespasses or breaks in.
Maintenance
Keep your yard mowed, remove any debris, and fix any issue that could deteriorate or become a larger problem. Winterize your plumbing if freezing could be an issue. It’s also a good idea to inspect the roof, gutters, and drainage systems before leaving the property vacant for an extended period.
Routine checkups
It’s a good idea to have someone drive by your property regularly to check for damage or vandalism. If you can, leave a car in the driveway to deter vandals and burglars. If possible, schedule or perform routine inspections to spot problems early, before they create substantial damage.
FAQ
Here are answers to common questions about vacant home insurance.
Are there differences between vacant property insurance and homeowners insurance?
Yes, and they are important in case you need to file a claim. Essentially, homeowners insurance assumes someone is living in the home, so it often has a vacancy clause. This clause means your coverage is limited or excluded if your home becomes vacant for more than 30 – 60 days.
Are vacant property insurance and unoccupied home insurance the same?
No. A vacant home is unoccupied, but it typically has no furniture or personal belongings. An unoccupied home is one with furniture and utilities, but isn’t being used for long periods of time – a vacation home is a good example.
Is vacant homeowners insurance worth it?
Probably. Like all insurance, you’re buying protection against what might happen. But considering the higher risks of vandalism, squatters, unattended burst pipes, and more, vacant property insurance could save thousands if tragedy strikes.
The bottom line: Vacant home insurance offers peace of mind
Hoping for the best with an asset as valuable and complex as a house really shouldn’t be your go-to option. And it’s very likely that your homeowners insurance policy doesn’t cover vacancies of months on end. Couple that with the fact that the risks to vacant homes are heightened, and a vacant home insurance policy is well worth considering. If nothing else, it will offer peace of mind. And that’s priceless. If you’re leaving a home vacant and looking for something new, connect with one of our Home Loan Experts to go over your financing options.
Rocket Mortgage is a trademark of Rocket Mortgage, LLC or its affiliates.
Terence Loose
Related resources
9-minute read
What is homeowners insurance?
Read more
8-minute read
Is homeowners insurance required? What buyers should know
Is a homeowners insurance policy required? Insurance is not legally required, but your lender will require you to carry a policy to protect its investment.
Read more
5-minute read
What Is renters insurance? Defined and explained
Renters insurance is a way for renters to protect themselves and their belongings when renting property. Learn about what’s covered with renters insura...
Read more